Published: 19 September 2026 | Last updated: September 2026 | Tax year: 2026/27 | Reviewed by Shamayun Chowdhury, CIMA
To grow a small business in the UK, pick one main lever (selling more to existing customers, winning new ones, charging better prices, or adding a product or market), set a measurable target and check your cash can fund it. Then plan for what growth brings with it: VAT registration, payroll and extra tax admin.
Most growth advice stops at the tactics. This guide goes one step further. It helps you decide which lever suits your business right now, shows the tax and employment thresholds you are likely to cross on the way, and ends with a 90-day plan you can start on Monday.
On this page
- Are you ready to grow? A 10-point check
- The four ways a small business grows
- Choosing your growth lever
- Organic growth vs funded growth
- What growth triggers: UK tax and legal thresholds
- Worked example: from £70k to £110k turnover
- How to protect cash flow while you grow
- Free and subsidised UK growth support
- Common growth mistakes
- Your 90-day growth plan
- FAQs
Are you ready to grow? A 10-point check
Growth magnifies whatever is already there. A business with sound margins and tidy books gets stronger. A business that is busy but barely profitable just gets busier, and often more fragile. Before spending on growth, run through these ten points honestly.
- ☐ You have made a profit over the last 6 to 12 months, not just taken plenty of money in.
- ☐ You know your gross margin on your main products or services, as a percentage.
- ☐ You hold a cash buffer. A common rule of thumb is at least three months of fixed costs.
- ☐ Your bookkeeping is no more than a month behind, so the numbers you are deciding on are real.
- ☐ Demand is proven: repeat customers, a waiting list or work you have had to turn down.
- ☐ Core tasks are written down well enough that someone else could do them.
- ☐ You know where customers come from and roughly what each one costs you to win.
- ☐ You know your rolling 12-month turnover and how close it sits to the VAT threshold.
- ☐ Your personal finances can absorb a dip if growth costs arrive before growth income.
- ☐ You can protect time for growth work each week, away from day-to-day delivery.
Seven or more ticks and you are in a good position to grow. Fewer than five usually means the first job is fixing the foundations. That might mean sharpening your small business strategy before adding sales.
Fix these before you grow
Customers routinely paying late. A margin that has shrunk over the past year. More than about a third of sales coming from a single client. More work would make each of these worse, not better.
The four ways a small business grows
Almost every growth tactic you will read about is a version of one of four levers. Seeing them this way makes it easier to compare options and to avoid pulling all four at once.
1. Sell more to the customers you already have
This is usually the cheapest lever. Existing customers already trust you, so repeat orders, add-on services, maintenance plans and referral requests cost far less than finding strangers. If people buy once and never return, fix that first. Otherwise you are filling a leaking bucket.
2. Win new customers
This is the lever most owners think of first: advertising, content, partnerships, a better Google Business Profile. It works best when your offer is proven and you have spare capacity. Our guide to marketing on a small budget covers the channels in detail, so here the question is simply whether this is the right lever for you now.
3. Raise prices or improve your margin
Often overlooked and often the fastest. A modest price rise, a premium tier, or cutting a costly supplier or a product that loses money can lift profit without a single extra customer.
4. Add a product, service or market
New offers, new customer types, a second location or selling abroad. This lever has the highest ceiling and the highest risk, because you are testing demand again from scratch.
| Growth lever | Upfront cost | Speed | Risk | Best when |
|---|---|---|---|---|
| Existing customers | Low | Weeks | Low | Customers like you but buy only once |
| New customers | Medium | 1–6 months | Medium | Offer is proven and capacity is spare |
| Price / margin | Very low | Immediate | Low to medium | You are fully booked or margins are thin |
| New product or market | High | 6–18 months | High | Core market is saturated and finances are strong |
Choosing your growth lever: a simple decision framework
Work through these questions in order and stop at the first “yes”. That lever is your priority for the next quarter.
- Is your margin thinner than you would like, or falling? Start with price and costs. More sales at a poor margin simply means more work for the same money.
- Are you at or near full capacity? Raise prices, or invest in systems or help, before you market harder. Extra demand you cannot serve damages your reputation.
- Do fewer than half your customers come back? Work on retention and referrals before paying to acquire new people.
- Is demand proven, with capacity to spare? Now winning new customers is the right move.
- Has your core market stopped growing? Consider a new product, service or customer group, ideally tested small first.
Expert insight: price is the lever most owners pull last
An illustrative calculation. A business with a 30% gross margin raises prices by 5% and keeps the same volume. Its revenue goes from £100 to £105 per sale. Its costs stay at £70, so gross profit rises from £30 to £35. That is a 16.7% increase from a 5% price change.
It could lose roughly one in seven customers (about 14%) before ending up worse off. How many you would actually lose depends on your market and how clearly you explain the rise, so run your own numbers before deciding.
Organic growth vs funded growth: which suits you?
Organic growth is paid for out of your own profits. Funded growth uses someone else’s money, whether a loan, an overdraft, asset finance or an investor. Neither is better in principle. The right choice depends on how quickly the opportunity will disappear and how much risk you can carry.
| Organic growth | Funded growth | |
|---|---|---|
| Speed | Steady, limited by profit | Faster, if the plan works |
| Control | You keep all of it | Lenders set terms; investors take a share |
| Cost | Time and missed opportunities | Interest, fees or equity |
| Risk | Lower | Repayments continue even if sales dip |
| Suits | Service firms, owners who value independence | Proven models with a clear, time-limited opportunity |
A sensible middle route is to prove the growth idea organically on a small scale, then borrow to scale up what already works. If you are weighing lenders, grants or crowdfunding, our guide to funding options beyond a bank loan compares them side by side.
What growth triggers: UK tax and legal thresholds for 2026/27
This is the part most growth guides skip. As a business gets bigger, it crosses legal thresholds that bring new costs and paperwork. None of them should stop you growing, but each one is far easier to handle if you see it coming.
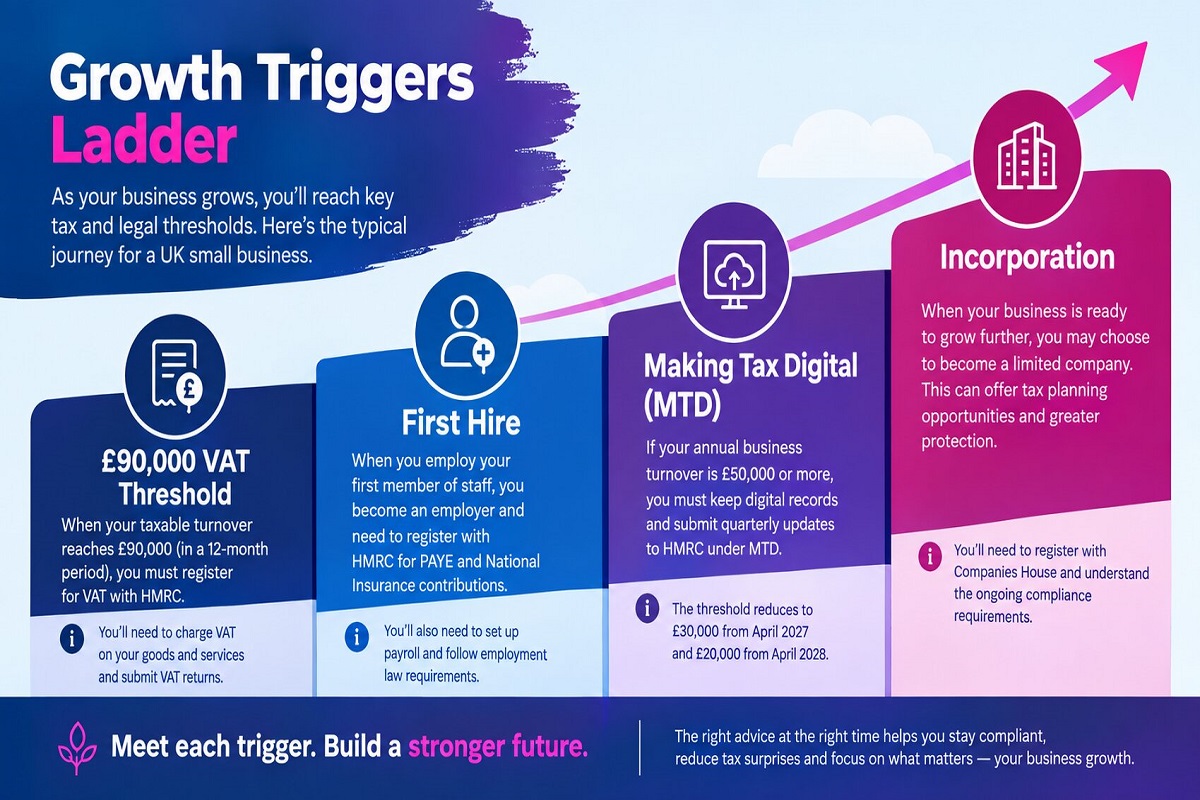
The VAT registration threshold: £90,000
You must register for VAT if your taxable turnover over the last 12 months goes over £90,000. The test runs on a rolling basis, not by tax year, so check it at the end of every month. You then have 30 days from the end of the month you went over to register, and you start charging VAT from the first day of the second month after you crossed the threshold, according to HMRC’s VAT registration guidance.
You must also register straight away if you expect to go over £90,000 in the next 30 days alone, for example after winning one large contract. For businesses that sell to the public, VAT is usually the biggest single shock that growth brings, because you either add 20% to your prices or absorb it from your margin. The worked example below shows the difference.
Taking on your first employee
Before the first payday you need to register as an employer with HMRC and run payroll through PAYE. Most employers also need employers’ liability insurance from the first day of employment. The ongoing costs are:
- Employer National Insurance at 15% on pay above £5,000 a year in 2026/27.
- Employment Allowance can cut that bill by up to £10,500 a year. The catch: a limited company whose only paid employee above the threshold is a director cannot claim it. Our sister site explains who can claim Employment Allowance in 2026/27.
- Workplace pension auto-enrolment: staff aged 22 to State Pension age earning over £10,000 a year must be enrolled, with an employer contribution of at least 3% of qualifying earnings. Employer duties start on the employee’s first day.
Making Tax Digital for Income Tax
Sole traders and landlords whose qualifying income (gross self-employment and property income, before expenses) was over £50,000 in 2024/25 have had to use Making Tax Digital for Income Tax since 6 April 2026. The threshold drops to £30,000 from April 2027 and £20,000 from April 2028, according to HMRC’s MTD eligibility guidance. Growing sole traders should expect to keep digital records and send quarterly updates through compatible software.
When incorporating becomes worth considering
There is no single profit figure at which a limited company becomes the right choice. It depends on how much profit you make, how much you take out, and how you value limited liability against extra admin. Companies pay Corporation Tax at 19% on profits up to £50,000 and 25% above £250,000, with marginal relief in between. Once profits rise steadily, it is worth modelling both options. Our comparison of UK business structures sets out the trade-offs.
| Trigger | When it applies | What you must do | Main cost |
|---|---|---|---|
| VAT | Taxable turnover over £90,000 in any rolling 12 months | Register within 30 days; file returns via MTD software | 20% on standard-rated sales, less VAT reclaimed |
| First employee | Before the first payday | Register as an employer; run PAYE; arrange liability insurance | 15% employer NI above £5,000 (Employment Allowance may offset it) |
| Auto-enrolment | Staff aged 22+ earning over £10,000 | Enrol, contribute, declare compliance | At least 3% of qualifying earnings |
| MTD for Income Tax | Qualifying income over £50k (2026), £30k (2027), £20k (2028) | Digital records; quarterly updates | Software and admin time |
| Incorporation | Your choice, usually as profits rise | Register with Companies House; file accounts | Accountancy fees; Corporation Tax 19–25% |
Worked example: growing from £70k to £110k turnover
Illustrative scenario. The business and figures are invented to show how the numbers work and do not describe a real person.
A sole-trader decorator works mainly for homeowners, who cannot reclaim VAT. Turnover is £70,000, and materials cost about 20% of what customers pay. Demand is strong, and the owner is thinking about taking on enough extra work to reach £110,000. We compare three routes:
- A. Hold turnover just under the threshold, at £89,000.
- B. Grow to £110,000 of customer payments, register for VAT and keep prices the same, so the VAT comes out of the margin.
- C. Raise prices by 10% before registering, and do the same volume of work as in B.
| A: stay under | B: grow, absorb VAT | C: grow, raise prices | |
|---|---|---|---|
| Paid by customers | £89,000 | £110,000 | £121,000 |
| Less VAT due to HMRC (1/6 of receipts) | £0 | −£18,333 | −£20,167 |
| Sales kept by the business | £89,000 | £91,667 | £100,833 |
| Materials (net of any VAT reclaimed) | −£17,800 | −£18,333 | −£18,333 |
| Gross profit | £71,200 | £73,333 | £82,500 |
What the numbers show. Route B means roughly 24% more jobs for just £2,133 more gross profit, because nearly all the extra income goes on VAT. Route C does the same volume of work and earns £11,300 more than A. The lesson is not to avoid the VAT threshold. It is to plan your prices before you cross it, and to check whether the VAT Flat Rate Scheme would help.
Two further points. At this turnover the decorator is likely to be inside Making Tax Digital for Income Tax already, if their 2024/25 qualifying income was over £50,000. And for businesses selling mainly to VAT-registered customers, the picture changes completely, because those customers can reclaim the VAT you charge.
How to protect cash flow while you grow
Profitable businesses can still run out of money. The usual cause during growth is overtrading. You pay for staff, stock and materials now, but customers pay you weeks later. The faster you grow, the bigger that gap becomes.
The simplest defence is a rolling 13-week cash forecast, updated every Friday:
- Start with today’s bank balance.
- List the money you realistically expect in each week, based on when customers actually pay rather than when invoices fall due.
- List every outgoing, including VAT, PAYE and tax payments on their real due dates.
- Look for any week where the balance dips below your safety buffer, and act before it arrives.
Other practical moves:
- Take deposits on larger jobs.
- Invoice the same day the work is done.
- Offer card or instant bank payment.
- Move tax money into a separate savings account every time you are paid.
Free and subsidised UK growth support
Several publicly backed schemes exist to help small firms grow. Availability and eligibility change, so check the current terms before applying.
| Support | What it offers | Who it suits |
|---|---|---|
| Help to Grow: Management | A 12-week leadership course run by accredited business schools, with 1:1 mentoring. It is 90% government-funded, so participants pay £750. | UK SMEs with 5–249 employees that have been trading for at least a year |
| Local business support | Free advice, workshops and signposting. In England this is your local Growth Hub; elsewhere it is Business Gateway (Scotland), Business Wales and Invest NI. | Any business, including sole traders |
| British Business Bank | Government-backed finance, including Start Up Loans for younger businesses, plus guidance on finance options | Businesses that need to borrow to grow |
| Mentoring | Free or low-cost guidance from experienced owners | Owners who want an outside view on decisions |
Common growth mistakes
- Chasing turnover instead of profit. A bigger top line means nothing if the margin shrinks. Track gross profit every month, not just sales.
- Hiring before the work is steady. A first hire is a fixed monthly cost. Test demand with freelancers or overtime first.
- Missing the VAT threshold. Registering late means you still owe VAT on sales since the date you should have registered, and a penalty may apply on top.
- Staying the bottleneck. If every quote, decision and invoice goes through you, growth stops when your diary is full.
- Pulling every lever at once. New products, new marketing and new staff in the same quarter make it impossible to tell what worked.
- Growing on overdraft by accident. If the account keeps dipping, you are funding customers with credit you never planned to take.
Your 90-day growth plan, step by step
- Week 1: get your baseline. Write down turnover, gross margin, cash buffer, customer numbers and your rolling 12-month VAT turnover.
- Week 2: choose one lever. Use the decision framework above. Write down why you chose it.
- Week 2: set one target. One number and one date, such as “raise repeat bookings from 30% to 40% by 31 December”.
- Week 3: budget and diarise triggers. Cost the plan, update your 13-week cash forecast, and note any threshold you might cross.
- Weeks 3–11: execute and measure weekly. Protect a fixed block of time each week for the growth work.
- Weeks 12–13: review. Keep what worked, drop what did not, and choose the next lever for the following quarter.
FAQs
How can I grow my business quickly?
The quickest results usually come from pricing and existing customers, not new marketing. A well-explained price rise lifts profit straight away. Asking happy customers for repeat work and referrals costs little and converts well. Save bigger bets, like new products or markets, until the core business is running smoothly and is properly profitable.
What is the cheapest way to grow a small business?
Selling more to the customers you already have is usually the cheapest route. They already trust you, so repeat offers, maintenance plans, add-on services and referral requests cost far less than winning strangers. Improving your margin through pricing or supplier costs is also low-cost, because it needs no extra sales at all.
Should I register for VAT before I reach £90,000?
It can make sense if most of your customers are VAT-registered businesses that can reclaim VAT, or if you buy a lot of standard-rated supplies. If you sell mainly to the public, registering early usually means charging 20% more or earning less. Model both options before deciding.
When should I hire my first employee?
Hire when the extra work is steady rather than seasonal, when it frees you for higher-value tasks, and when your cash forecast shows you can pay the salary through a quiet month. Remember that the true cost includes employer National Insurance, pension contributions and insurance, not just wages.
Is it better to grow organically or with funding?
Organic growth is slower but keeps you in control and carries less risk. Funding makes sense when you have a proven model and a clear, time-limited opportunity that profit alone cannot pay for quickly enough. Many owners prove an idea organically first, then borrow to scale what already works.
How do I grow my business without working more hours?
Raise prices, drop your least profitable work and write down repeatable tasks so someone else can do them. Automating invoicing, booking and reminders frees time as well. Growth that depends entirely on your personal hours will stall once your diary is full, so building systems is a growth strategy in its own right.
Next step: if VAT registration or a first hire is likely within the next year, run your numbers past an accountant before you cross the line. A pricing or timing decision made early is usually worth far more than a fix made afterwards.
About the author and reviewer
Written by Marina Jahan, content lead at Eternity Accountants.
Technically reviewed by Shamayun Chowdhury, Senior Accountant at Major Accountancy, Leicester, and Lecturer in Accounting at Nottingham Trent University.
Last reviewed: September 2026
This article is general information for the 2026/27 tax year and is not personal tax, legal or financial advice. Thresholds and rates can change, so check GOV.UK or speak to a qualified adviser about your circumstances.